Stay informed with our newest offers, policy updates, and financial insights.
Simple videos on insurance, investments, and tax planning.
Loading videos...
Select a category to explore plans built around your life goals.
Term, health, and property insurance tailored to your family's needs — your safety net for life's uncertainties
High-value life cover at the lowest possible premium. ₹1 Cr cover for your family starting at just ₹501/month
Comprehensive coverage for hospitalisation, critical illness, and surgery — with family floater options
Mutual funds, shares, real estate, and fixed income — every instrument aligned to your risk profile and return expectations
Life cover AND investment returns in one plan — your family stays protected while your money actively grows
Unit-linked plans that invest in equity and debt funds — flexible, transparent, and market-linked with life cover
Equity, debt, and hybrid funds aligned to your goals — managed by India's top fund houses with goal-mapped selection
Direct equity investments with research-backed stock picks, portfolio management, and Demat account setup support
Fixed, tax-free payouts with no market risk — know exactly what you'll get, 100% capital protected
Education, marriage, retirement — every recommendation mapped to your actual life milestones and timeline
Corpus building and regular pension income — plan your retirement with top-rated funds and inflation-adjusted payouts
Systematic savings for your child's higher education including international studies — secured today, harvested when needed
A dedicated long-term savings plan to build a strong marriage fund for your daughter — planned, protected, and fully tax-free
Holistic Wealth Planning
Just like a balanced Indian meal brings together the right mix of elements, your finances need a thoughtful combination of protection, growth, liquidity, and stability to support every stage of your life journey.
Every financial life is unique. Your Kundli is a comprehensive assessment across four critical dimensions — crafted to understand your reality before we ever recommend a solution.
A clear picture of how money moves through your life is the foundation of every sound financial decision. We map every inflow, every commitment, and every savings opportunity — month by month.
Every person you are responsible for changes what your financial plan must do. We map your dependents' timelines, your loan exposures, and every fixed commitment — so your plan is built around your real life, not a hypothetical one.
Your goals are not vague aspirations — they are financial targets with a price and a deadline. We convert every milestone into a corpus requirement, a timeline, and a funding strategy tailored to your savings capacity.
Risk tolerance is not a questionnaire score — it is the intersection of your emotional comfort, your financial capacity, and the specific time horizon of each goal. Getting this right is what keeps you invested when markets become uncomfortable.
A 45-minute session where we review your complete financial picture across all four dimensions — no product pitches, no pressure, just absolute clarity on where you stand and what deserves attention first.
Every financial need — planned, balanced, and aligned to your life.
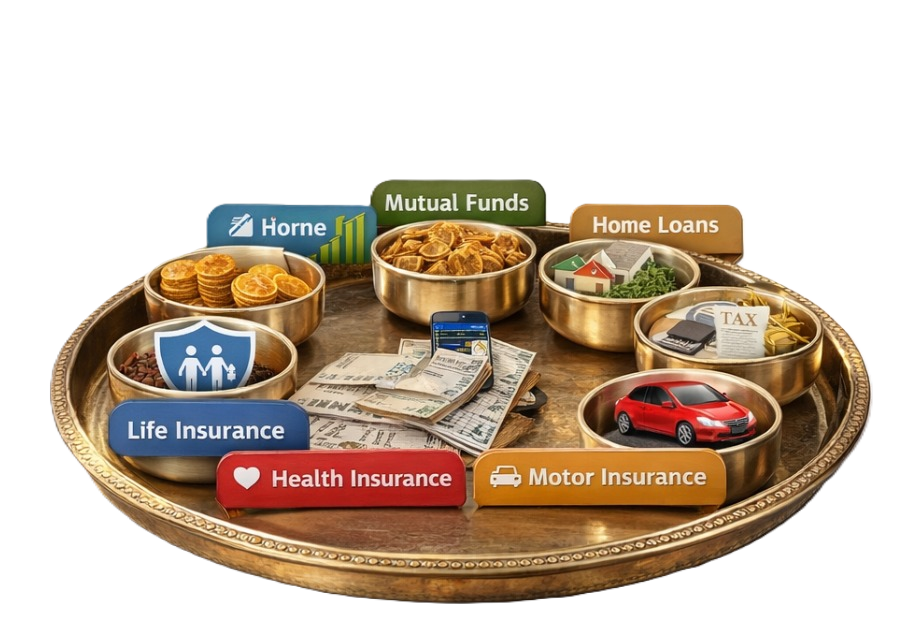
Not everyone needs the same financial solutions. Based on your current situation, some products may be more urgent than others.
You need term insurance if you have dependents, home loans, or future financial responsibilities that require income replacement.
You need health insurance if you don't have employer coverage, have family medical needs, or want critical illness protection.
You need mutual funds if your goals are 5+ years away and you can handle some market volatility in exchange for higher long-term growth.
You need fixed deposits if you prefer predictable returns, are building an emergency fund, or have short-term financial goals within 1–3 years.
"The right product at the wrong time is still the wrong decision. Let's check what's right for you."
Real stories from families who chose to protect their future with us. View more
"I had SIPs, some LIC policies, and a home loan — but no clear idea of how they connected. Saptarshi ji helped me see the full picture. He identified that my life cover was significantly less than my loan liability and restructured the plan completely. Now I feel genuinely secure, not just financially active."
"As a government servant, I always assumed my pension was enough and I did not need to plan beyond that. Saptarshi ji showed me, with actual numbers, that my daughter's MBA abroad and our retirement lifestyle both required separate, dedicated planning starting now. That conversation changed how I think about money."
"My husband and I both earn well, but our savings never seemed to grow. We had separate accounts, different advisors, and no shared financial plan. Saptarshi ji brought everything together — one clear picture, one coordinated strategy. Within six months, we had our first proper emergency fund and a structured SIP plan tied to our children's education."
Dear Client,
Let's meet for a
No selling. Just a courtesy 20-min meeting to review your financial health & goals.
Let's connect. Please share a suitable time to meet.